Stockpiling, manufactured scarcity, and the laboratory-grown revolution threatening the foundations of the natural gemstone industry.
The Diamond Giants Are in Trouble
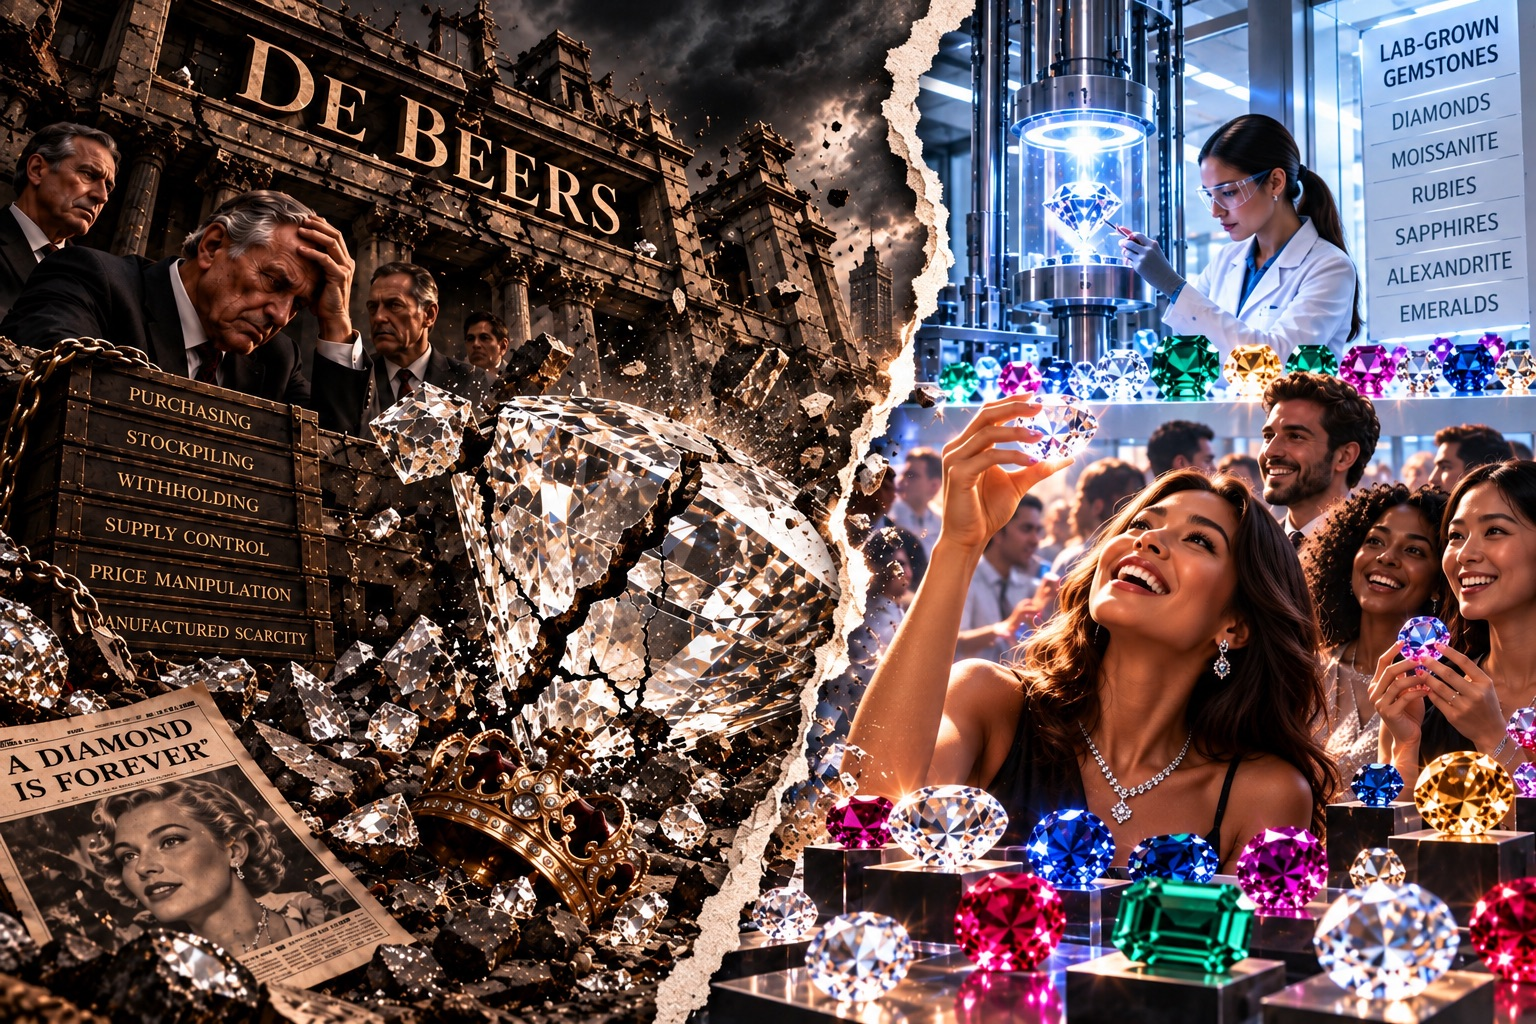
The diamond industry is confronting a threat it can no longer contain through stockpiling, supply restrictions, or carefully manufactured perceptions of scarcity.
For decades, a handful of powerful companies exercised enormous influence over the global diamond trade, shaping availability, prices, and consumer expectations. Diamonds became symbols of wealth, prestige, and financial security, supported by the belief that their extraordinary prices reflected extraordinary rarity.
De Beers stood at the center of that system.
For much of the twentieth century, the company dominated the rough-diamond trade through mining interests, purchasing agreements, stockpiling, and centralized distribution.
De Beers accumulated enormous diamond inventories through purchasing arrangements and stockpiling, allowing the company to withhold diamonds from the market, restrict available supply, and support artificially elevated prices while promoting the belief that diamonds were exceptionally rare.
The company’s influence extended beyond supply. Its marketing helped transform diamonds into symbols of eternal love, exclusivity, and lasting value. The famous slogan A Diamond Is Forever became one of the most successful advertising campaigns in commercial history.
Yet diamonds are not uniformly rare. Exceptional natural diamonds can be extraordinarily scarce, but ordinary commercial-quality stones do not possess the same geological exclusivity.
The retail price of a natural diamond has never been determined by geological rarity alone. Branding, grading, distribution, consumer expectations, and control over supply have all contributed to its market value.
De Beers no longer commands the market as it once did. Other major producers operate independently, and the historical supply structure has weakened.
Now the industry faces a competitor it cannot control by purchasing more mines or withholding additional inventories.
Chemistry has broken the supply barrier.
Chemistry Has Standardized What Was Once Exclusive
Decades of scientific research have transformed gemstone production from a process dependent on geological discovery into one increasingly controlled by manufacturing technology.
A laboratory-grown diamond is a diamond. It possesses the same crystalline carbon structure and essential physical and chemical properties as its natural counterpart.
The same applies to laboratory-grown rubies, sapphires, and alexandrites when their mineral composition and crystal structures correspond to those found in nature.
Laboratory diamonds are principally manufactured through two methods.
High Pressure, High Temperature (HPHT) exposes carbon to extreme conditions that permit diamond crystal growth. Chemical Vapor Deposition (CVD) uses carbon-containing gases to deposit carbon onto a crystalline substrate, gradually forming diamond.
Rubies, sapphires, and other gemstones can be grown using flame fusion, flux growth, or hydrothermal techniques.
Moissanite belongs to a different mineral family. Composed of silicon carbide, it is not diamond, nor is it chemically identical to one. Its hardness, brilliance, exceptional fire, and resistance to everyday wear have nevertheless made laboratory-grown moissanite a formidable jewelry alternative.
Manufacturing has made gemstone beauty and durability accessible without requiring the financial resources once associated with natural stones.
A diamond’s geological origin can still command a premium. Its optical beauty, however, is no longer exclusive to mining.
De Beers’ Financial Troubles Expose the Pressure
The industry’s difficulties are no longer confined to speculation.
In its 2025 financial results, Anglo American, De Beers’ parent company, reported a $2.3 billion impairment associated with the diamond business. Changing consumer preferences, competition from laboratory-grown diamonds, and weak market conditions contributed to the pressure on its valuation.
The laboratory-grown industry has experienced a different kind of disruption.
According to diamond market analyst Edahn Golan, laboratory-grown diamond wholesale prices declined approximately 26% during 2025.
In a conventional luxury market, a sharp price decline might be interpreted as evidence of collapsing desirability.
In a manufacturing market, it can signal something else: expanding supply, improving production efficiency, intensifying competition, and the correction of prices that were initially too high for the customers the product could reach.
The laboratory-grown market may have inherited a pricing strategy designed for natural gemstones while overlooking the purchasing power of its own potential customers.
Selling an affordable alternative at a luxury premium restricts the very audience that makes the product commercially disruptive.
As production costs decline and competition expands, manufacturers have greater room to serve customers who were never participants in the traditional luxury gemstone market.
That distinction challenges the prevailing explanation for the natural diamond industry’s decline.
Two Markets, Two Different Customers
The natural gemstone industry and the laboratory-grown gemstone industry do not necessarily compete for the same customers.
The traditional interpretation assumes that a consumer purchasing a laboratory-grown diamond represents a consumer who would otherwise have purchased a natural diamond.
But a customer unwilling or unable to spend $15,000 on a natural diamond ring may willingly spend $1,000 on a laboratory-grown alternative.
That is not necessarily a lost $15,000 sale. It may be a newly created $1,000 sale.
The laboratory-grown industry is not simply dividing the existing gemstone market. It is opening that market to consumers previously excluded by its prices.
The purchasing motivations are also different.
Natural Gemstones: Prestige and Capital Preservation
For an important segment of affluent buyers, natural gemstones represent more than attractive minerals.
They represent status, provenance, perceived rarity, wealth preservation, and potential appreciation.
The purchase is partly an acquisition of an asset whose exclusivity is expected to endure.
Luxury collectible markets operate on similar expectations. A discontinued Hermès handbag can command a substantial secondary-market premium when collectors compete for an item whose production has ended.
The resale value may bear little relationship to its original manufacturing cost.
Exceptional natural gemstones can benefit from comparable collector demand.
But the same investment expectations have also been attached to ordinary natural gemstones whose rarity and secondary-market liquidity may not justify their retail premiums.
Laboratory-Grown Gemstones: Beauty Without the Investment Premium
Laboratory-grown gemstone customers can pursue an entirely different objective.
They want beauty, color, brilliance, durability, personal enjoyment, and affordability.
They are not necessarily interested in acquiring a geological specimen as an investment or paying a premium for its natural origin.
A laboratory-grown gemstone offers the opportunity to purchase the desired material and appearance without accepting the financial assumptions attached to the traditional natural gemstone market.
These customer groups are not completely separate. Some natural gemstone buyers also purchase laboratory-grown stones, and some laboratory-grown customers value luxury and prestige.
Nevertheless, the expansion of laboratory-grown jewelry does not require a corresponding migration of wealthy natural gemstone buyers.
A substantial portion of that growth may come from people who were never willing to pay natural gemstone prices in the first place.
The Natural Gemstone Industry’s Real Threat: Investment Confidence
The natural gemstone market faces a problem that laboratory-grown competition alone cannot explain.
Its customers may begin questioning whether ordinary natural gemstones are reliable stores of value.
A wealthy buyer does not need to switch to laboratory-grown diamonds to reduce spending on natural diamonds. The buyer can simply stop purchasing them.
Capital can be redirected toward other assets. Purchases can be postponed. Existing gemstone inventories can be retained rather than expanded.
The fear of depreciation can weaken demand independently of the availability of cheaper alternatives.
For years, natural gemstones benefited from an association between high retail prices, exclusivity, and lasting financial value.
But retail price is not resale value.
A natural diamond purchased at a substantial retail premium may later be worth considerably less in the secondary market. Dealer margins, grading differences, market liquidity, and changing demand can all affect the amount a seller recovers.
When buyers begin questioning whether the premium is recoverable, the investment argument loses part of its influence.
The natural gemstone industry’s vulnerability is therefore not limited to consumers choosing laboratory-grown alternatives.
It also lies in wealthy buyers losing confidence that ordinary natural gemstones deserve the prices being demanded for them.
The Certification Problem: A Premium for an Invisible Difference
Laboratory-grown diamonds create another difficulty for natural gemstone pricing.
A laboratory-grown diamond and a natural diamond can be virtually indistinguishable through ordinary visual examination.
Both possess the same essential mineral composition and physical properties. Conventional diamond testers generally cannot establish geological origin.
Specialized gemological instruments and advanced analytical methods may be required.
The Gemological Institute of America and other laboratories possess techniques capable of distinguishing natural from laboratory-grown diamonds. However, screening limitations, identification errors, grading disagreements, and inconsistent terminology across institutions complicate the consumer’s understanding of what is being purchased.
A grading report is not an infallible guarantee of future resale value.
Nor do all gemological institutions apply identical grading standards or terminology.
The natural diamond’s substantial origin premium consequently depends on trusted documentation, reliable identification, and confidence in the institutions performing those evaluations.
The consumer may be asked to pay thousands of dollars more for a distinction that cannot be verified by appearance alone.
Why accept that premium, and the associated verification risk, when an optically comparable laboratory-grown diamond offers the same essential material properties at a fraction of the price?
For a collector seeking a genuinely rare natural specimen, documented origin may justify the expense.
For an ordinary jewelry buyer seeking beauty and durability, the financial justification is far less convincing.
Laboratory-Grown Gemstones Can Compete at Every Price Level
The laboratory-grown industry possesses a structural advantage: manufacturing flexibility.
Gemstones can be produced and marketed across different sizes, clarity grades, colors, cuts, and quality categories.
Manufacturers can serve entry-level customers, middle-income buyers, premium jewelry consumers, and luxury clients without depending on the unpredictable discovery of natural deposits.
Market
Gemstone offering
Customer priority
Entry level
Small or commercial-grade stones
Affordability
Mid-market
Attractive, well-cut stones
Beauty and durability
Premium
Larger, higher-quality stones
Visual excellence
Luxury
Exceptional stones in distinctive settings
Design and craftsmanship
Not every laboratory-grown gemstone is inexpensive to manufacture. Equipment, energy, cutting, labor, and distribution impose real costs.
Nevertheless, manufacturing technology allows production methods to improve, capacity to expand, and costs to decline.
Natural gemstone producers cannot increase geological deposits on demand. They must locate, mine, and process deposits whose quality and availability vary.
The laboratory-grown industry can therefore reach a wider range of purchasing power while continually adjusting its product offerings.
The consequences are particularly significant for the lower and middle segments of the natural gemstone market.
When affordable alternatives offer comparable beauty and durability, ordinary natural stones must justify the additional price attached to their origin.
Manufactured Scarcity Is Losing Its Pricing Power
The historical diamond industry benefited from a broad commercial association between natural origin and rarity.
Laboratory-grown production challenges that association.
A natural stone is not necessarily an exceptionally rare stone.
Natural diamonds exist across enormous variations in size, color, clarity, and quality. The same distinction applies to rubies, sapphires, emeralds, and other gemstone categories.
Yet ordinary natural stones have frequently been marketed within a luxury framework that encourages consumers to associate geological origin with enduring value.
As laboratory-grown gemstones become more accessible, that association may become increasingly difficult to sustain.
Stockpiling natural diamonds cannot create a shortage of laboratory-grown diamonds.
A supply strategy that once supported the industry’s pricing power is therefore far less effective against an independently manufactured alternative.
Natural origin may continue to command a premium, but the market may increasingly demand evidence that a particular natural gemstone is genuinely exceptional.
An ordinary natural diamond cannot claim the same scarcity as an extraordinary natural fancy-color diamond.
A commercial-quality ruby cannot be valued on the same basis as a remarkable untreated ruby with exceptional color, size, and documented provenance.
The natural gemstone market may eventually lose its ability to charge extraordinary scarcity premiums for stones that are not genuinely scarce.
The Natural Gemstone Market on Thin Life Support
The natural gemstone market is unlikely to disappear. Its customer base may instead contract toward wealthy collectors, investors, and buyers who continue to value geological origin.
But not every natural gemstone will survive that contraction with its premium intact.
The market could increasingly divide into three categories.
Collector-grade natural gemstones would retain a specialized clientele seeking exceptional rarity, provenance, and historical or investment significance.
Ordinary natural gemstones would face weakening demand as consumers question the value of paying substantial premiums for relatively common material.
Laboratory-grown gemstones would expand across a broader customer base, competing through beauty, durability, price, and design.
A smaller natural gemstone market would not necessarily produce lower prices for every remaining stone.
Consider the following hypothetical market transformation.
Market indicator
Initial market
Future scenario
Natural gemstone buyers
100,000
55,000
Average natural purchase
$10,000
$13,000
Laboratory-grown buyers
150,000
800,000
Average laboratory-grown purchase
$800
$650
Illustrative scenario, not an industry forecast.
Under these assumptions, natural gemstone buyers decline by 45%, while the average purchase price increases by 30%.
The laboratory-grown customer base expands more than fivefold, despite a decline in its average transaction price.
The natural market becomes smaller and more expensive at the upper end. The laboratory-grown market becomes larger and more accessible.
Average natural gemstone prices could rise because lower-priced buyers and products have disappeared from the market, not because every remaining stone has appreciated.
The industry’s total natural gemstone sales revenue would still decline substantially in this example.
The market would be losing customers while becoming more concentrated around higher-value transactions.
Only Genuine Rarity May Preserve the Natural Gemstone Premium
The eventual correction could produce a more selective natural gemstone market.
Rather than treating natural origin itself as an investment qualification, collectors may increasingly concentrate on stones possessing exceptional and verifiable characteristics.
Extraordinary natural colors, unusual sizes, exceptional clarity, untreated condition, documented provenance, and historical significance could become more important.
Stones that cannot demonstrate meaningful rarity may struggle to retain the premiums established under the traditional pricing system.
The surviving collector market could remain highly profitable for exceptional specimens while ordinary natural gemstones experience weaker demand and declining resale expectations.
Genuine rarity does not guarantee appreciation. Even exceptional gemstones remain exposed to liquidity constraints, changing collector preferences, and economic downturns.
But the basis for their premiums would be more closely connected to the scarcity of the individual specimen than to the broad marketing value of natural origin.
The natural gemstone industry’s future may depend on how convincingly it can distinguish genuinely rare stones from ordinary material historically sold under the same luxury narrative.
Democratization: The End of Exclusive Access
The laboratory-grown revolution threatens more than the pricing structure of natural gemstones.
It challenges the competitive advantages of established jewelry houses.
Historically, entry into high-end jewelry design required considerable capital.
Natural gemstone inventories, sourcing relationships, specialized manufacturing, and access to distribution networks created barriers that favored established companies.
Laboratory-grown gemstones reduce the cost of entering that market.
An independent designer can now develop sophisticated jewelry using beautiful, durable stones without committing substantial capital to expensive natural gemstone inventories.
Manufacturing can be outsourced to specialist workshops. Precision setting, metal finishing, stone cutting, and advanced fabrication techniques are no longer exclusively accessible to the largest jewelry houses.
The resulting competition changes what consumers can demand.
Why pay $20,000 for a conventional design from an established jewelry house when an independent designer may offer a more original, precisely manufactured piece for $3,000?
The established brand may still command a premium through heritage, reputation, customer service, and collector demand.
But access to attractive gemstones is no longer sufficient to justify that premium.
As laboratory-grown gemstones become widely available, the difference between competing jewelry products increasingly depends on originality, proportions, precision, craftsmanship, durability, and price.
Large jewelry houses retain enormous advantages in marketing and distribution. They no longer possess the same advantage in access to visually impressive gemstones.
Independent designers can compete on the quality of the finished creation rather than the financial resources required to acquire its central stone.
A market once dominated by access to expensive materials becomes increasingly accessible to creators whose principal assets are design and technical execution.
The End of a Monopoly Era
The laboratory-grown gemstone revolution is dismantling one of the traditional industry’s most important commercial advantages: the ability to associate gemstone beauty and durability with restricted access to natural supply.
De Beers’ historical dominance demonstrated how purchasing arrangements, stockpiling, centralized distribution, and marketing could sustain elevated prices through controlled availability and cultivated perceptions of scarcity.
That model cannot operate with the same effectiveness in a market where manufacturers can independently produce diamonds and other gemstones with equivalent essential mineral properties.
The natural gemstone industry’s difficulties cannot be explained solely by customers abandoning natural stones for cheaper alternatives.
Laboratory-grown gemstones are opening an accessible market for consumers whose purchasing motivations differ from those of traditional luxury buyers.
Meanwhile, affluent natural gemstone customers may become increasingly cautious about the investment value of ordinary stones.
The natural market could contract toward a smaller group of genuinely exceptional specimens, while laboratory-grown gemstones expand across a broader range of incomes and consumer preferences.
The consequences will extend throughout the jewelry industry.
Manufacturers will compete on efficiency. Established luxury houses will face growing pressure to justify their premiums. Independent designers will gain access to materials and manufacturing opportunities previously constrained by capital.
The value of ordinary natural gemstones may become increasingly difficult to defend through origin alone.
The value of genuinely rare natural specimens may become more closely tied to demonstrable scarcity and collector demand.
And the value of finished jewelry may depend increasingly on the originality, precision, and craftsmanship of its creation.
Stockpiling can restrict the supply of natural diamonds. It cannot restrict the supply of laboratory-grown diamonds.
The industry can continue selling natural origin as a luxury distinction. What it can no longer assume is that every consumer will pay an extraordinary premium for it.
The monopoly era is ending. The era of manufactured scarcity is being challenged by manufactured abundance.
This version removes repeated explanations, restores the explicit mechanisms of stockpiling and supply manipulation, and keeps the article’s conclusions forceful without explaining to readers what they should think.
The financial figures and historical claims should receive a final source check before publication. The market projections remain clearly identified as hypothetical.
The Gatekeepers Have Fallen: How Social Media and AI Broke the Monopoly on Truth
AI and Social media will remain the crowd’s accountability weapon. Political corruption, corporate abuse, even personal misconduct, nothing will stay hidden.
For most of the 20th century, the story of the world was told by a select few. A handful of newspapers, radio stations, and television networks dictated what the public saw, heard, and believed. The gatekeepers decided which wars were “just,” which leaders were “good,” and which scandals were “worth covering.”
The arrangement was simple: control the narrative, and you control the people. For decades, it worked flawlessly.
Then came social media. Then came artificial intelligence.
And the flood gate open.
When the Broadcast Tower Fell
Social media didn’t just connect people, it shattered the top-down broadcast model. No longer were we passive spectators; we became participants, fact-checkers, and sometimes, the news itself.
The Arab Spring (2010–2012) offered one of the first global shocks to the system. Twitter, Facebook, and YouTube bypassed state-controlled media in Tunisia, Egypt, and beyond, showing protests, police brutality, and raw footage the world was never meant to see. Governments realized, too late, that the public now had its own printing press.
In the West, events like WikiLeaks (2010) and Edward Snowden’s NSA revelations (2013) cracked the illusion of benevolent, transparent governance. Suddenly, information suppression wasn’t a fringe conspiracy theory, it was demonstrable policy.
Where once we took the evening news at its word, now a single viral clip, leaked PDF, or smartphone video could dismantle an official narrative in hours.
The Rise of the Second Opinion State
Social media is now the largest “second opinion” network in human history.
Hear a claim? You check X, Reddit, or TikTok. See breaking news? You scan livestreams, comment threads, and independent reporters to see what’s being left out.
But there’s a darker side. People are no longer just consuming news, they are consuming the news they want to hear. Echo chambers solidify. Confirmation bias spreads algorithmically. What’s “true” becomes secondary to what feels rightto the individual.
And social media doesn’t just challenge institutions, it challenges individuals. A racist outburst in a store, a viral video of misconduct, or an offensive post from years ago can ignite a global backlash in hours. Jobs are lost, reputations erased, careers ended, not by a court ruling, but by a decentralized digital jury. The same tool that exposes systemic corruption also exposes personal misconduct with brutal efficiency.
AI: Breaking the Locks on Skill
If social media liberated information, AI is liberating capability.
For centuries, access to skill and knowledge was gated behind wealth. Universities charged crippling tuition. Research was locked behind paywalls. Professional fields demanded expensive credentials. Intelligence mattered less than access, and access was sold to the highest bidder.
Now, the floodgates are open.
The tools they never meant for everyone to have are in everyone’s hands. A teenager with a laptop can generate photorealistic images, write like a seasoned journalist, or build an app from scratch. The $100,000 degree is being undermined by a free prompt and a good idea.
This is a direct assault on the old knowledge economy, a collapse of the wealth-based hierarchy that maintained institutional control. The tollbooths are breaking. The gatekeepers are losing their leverage.
The Unintended Chaos
Here’s the catch:
The very tech giants who built these tools for dominance may have triggered their own downfall. By giving billions unfiltered access to the world, and the means to process, remix, and redistribute it instantly, they destroyed the trust cycle that held the old order together.
Governments and legacy media can no longer predict how citizens will react, because citizens are now unpredictable by design.
Their response? Label dissent as “misinformation.” Regulate the platforms. Shadowban voices. Throttle reach. In places like China, Iran, and even parts of the West, policies are quietly emerging to monitor, suppress, or algorithmically bury content that challenges official lines.
But the genie is out. The information, and the capability to wield it, is decentralized.
The Forecast: What Comes Next
1. Citizen Media Will Rise
Trust in traditional outlets will continue to erode. Independent voices, small collectives, and decentralized reporting networks will dominate breaking news. Livestreams, drones, and open-source verification will replace studio segments. People won’t wait for polished packages, they’ll watch raw footage in real time.
2. Censorship Will Disguise Itself as Safety
Governments will pass laws forcing platforms to delete content within hours or face crippling fines. Corporate investors will pressure companies to comply with “stability guidelines.” Subsidies will reward obedience. Board seats and user data access will be quietly negotiated.
The blueprint is already here:
Facebook–Cambridge Analytica (2018): Mass data harvesting weaponized for political targeting.
Twitter Files (2022–2023): Internal docs revealing government-driven content suppression during elections and public health crises.
TikTok Geopolitics: Ongoing U.S. efforts to force a domestic sale under the guise of “national security” while angling for control of its algorithm.
3. War on Viral Upstarts
Emerging platforms that grow too fast will be:
Bought out by government-affiliated investors.
Regulated out of existence under vague compliance laws.
Attacked in media campaigns until users flee.
This is not new. It’s the same strategy used in finance, pharmaceuticals, and tech: acquire or annihilate competition before it becomes uncontrollable.
4. AI Censorship Wars
Governments and corporations will deploy AI to detect and erase dissent before it trends. Official justification: public safety, national security, economic stability. Actual targets: whistleblowers, dissidents, rogue analysts.
The counter-move? Underground AI tools that encrypt, anonymize, and spread censored material in seconds. An arms race begins: suppression bots vs. liberation bots.
5. Decentralized Economies Will Emerge
As AI erodes the advantage of centralized infrastructure, solo operators will rise. A person in Lagos or Lisbon can now compete with firms in London or New York. Cryptocurrency, peer-to-peer payment systems, and freelance networks will bypass traditional banking and tax structures.
6. The Age of Personal Consequences
Social media will remain the crowd’s accountability weapon. Political corruption, corporate abuse, even personal misconduct, nothing will stay hidden. Court verdicts will matter less than viral judgment. Reputations will collapse in 48 hours or less.
7. Parallel Realities, Fractured Nations
People will stop consuming “the news” and start consuming their version of the news. AI-generated personalization will harden ideological divides. Shared reality will shrink. Policy-making will paralyze in nations where no two citizens agree on what’s real.
The Battle Isn’t Over
The monopoly on truth is broken. The monopoly on capability is broken.
But the fight for control of the pipes, the algorithms, and your digital identity is just beginning. The next decade won’t be about restoring the old order. It will be about surviving the new one.
The gatekeepers have lost their monopoly, but not their hunger. They will claw, bribe, and legislate to take back what slipped through their fingers.
History won’t remember the algorithms. It will remember who stood up when the code tried to shut them down.
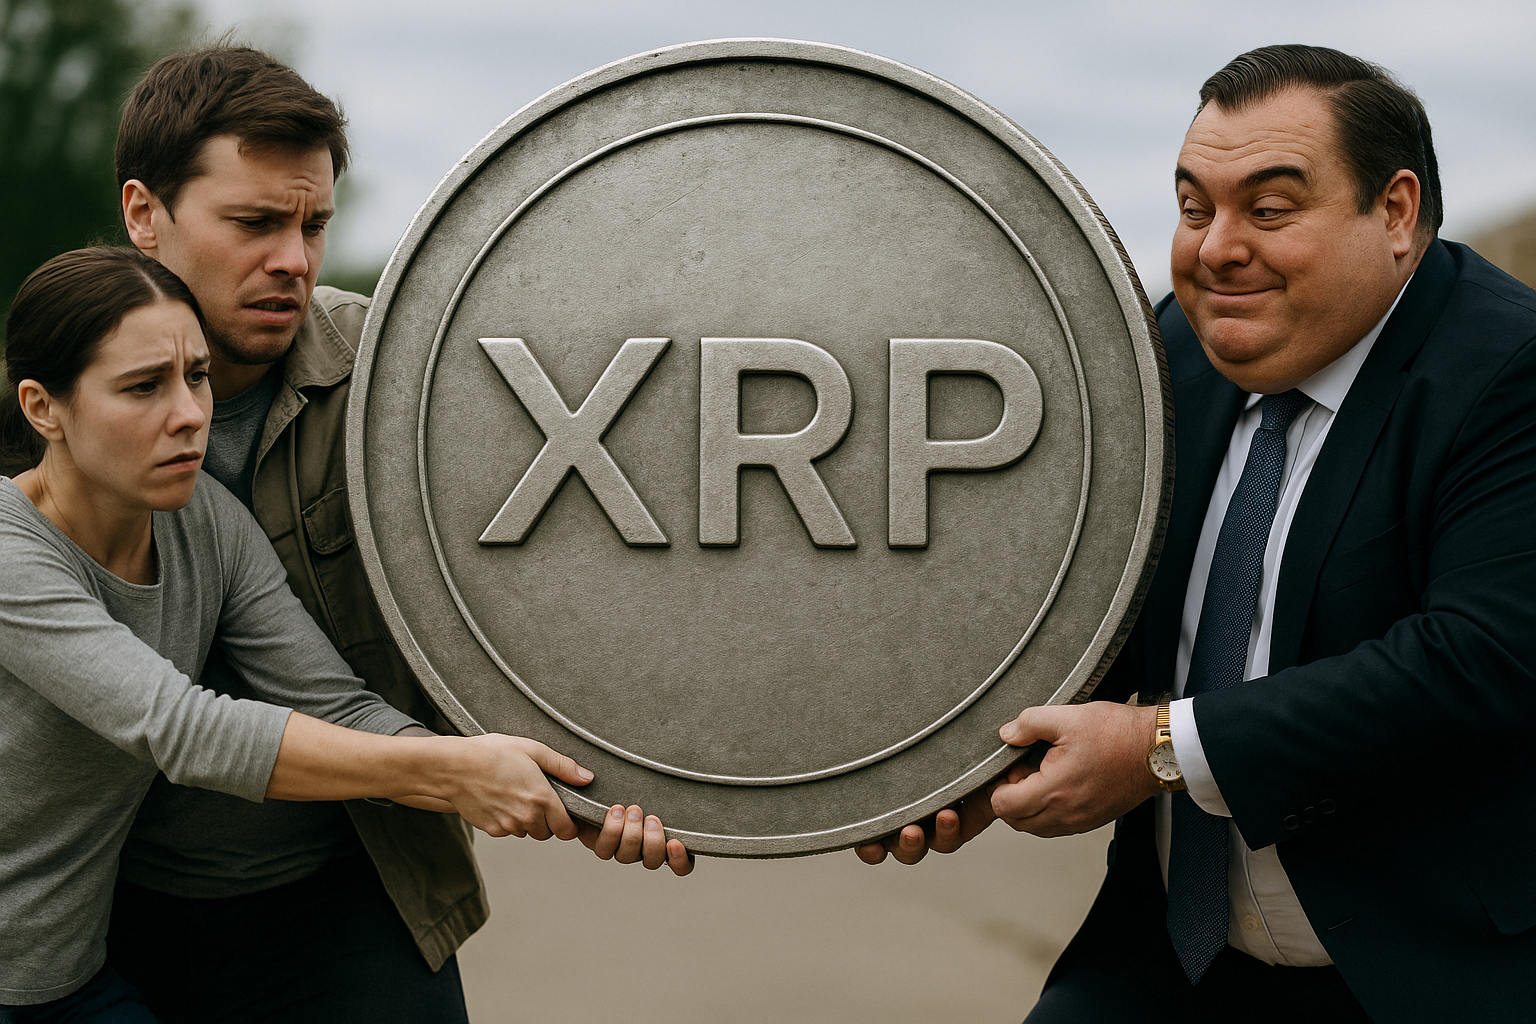
What if everything you thought about the SEC’s lawsuit against Ripple was a distraction? A clever mirage? What if the years-long legal spectacle was never about investor protection, but instead, a strategic smokescreen, designed to give financial institutions, governments, and hedge funds time to quietly seize control of one of the most promising digital assets in the world? The real story isn’t just about regulation. It’s about manipulation. And it played out right in front of us, while retail investors were told to stand back, wait, and hope.
Let’s follow the money. Let’s follow the timeline. And let’s finally expose the truth.
December 2020: The Trap Is Set
On December 22, 2020, the U.S. Securities and Exchange Commission filed a lawsuit against Ripple, accusing the company of selling $1.3 billion in unregistered securities through its XRP token. In the days that followed, XRP’s price plummeted. It was delisted from major exchanges. Panic spread across the retail market. And just like that, the asset was branded toxic.
But let’s ask the question no one wants to: who benefited most from XRP crashing below $0.30?
Retail investors had already built the foundation of the XRP ecosystem. By 2020, millions of small-scale holders had purchased XRP through Coinbase, Binance, Kraken, and dozens of other platforms. Wallet analysis confirms this: small and mid-sized holders controlled nearly 20% of the supply. These were regular people, not institutional whales. XRP, at its core, was a retail coin.
Then came the lawsuit. And like a perfectly timed market intervention, it froze enthusiasm, suppressed price, and halted new listings. Retail got spooked. Retail left. And that’s exactly what the institutions needed.
2021–2023: Accumulate in the Shadows
Over the next two years, the lawsuit dragged on. Page after page of legal filings, procedural delays, and strategic ambiguity. Yet during this slow legal burn, something else was happening behind the scenes. Whale wallets began to quietly grow. Entities with over one million XRP each accumulated billions. On-chain data revealed that by mid-2025, 2,743 wallets held over 47 billion XRP. That’s nearly 80% of the circulating supply.
Where did those XRP tokens come from?
They didn’t magically appear. They were acquired during a period when the market was scared, exchanges were delisting, and headlines were shouting danger. The irony? While the SEC claimed it was protecting retail investors, it was creating the perfect window for institutions to buy in silence.
And buy they did.
Major transfers to Coinbase and other institutional custody services began to spike. Whale Alert flagged transactions in the tens of millions. Funds flowed in. Traditional capital, once too cautious to touch XRP, now had an excuse to quietly take positions while the public eye was fixated on the courtroom.
2023: The Smoke Begins to Clear
In July 2023, Judge Analisa Torres ruled that XRP’s programmatic sales to retail investors were not securities. It was a blow to the SEC’s position. But by then, the damage, or the strategy , was done. Institutional sales were still deemed securities, but that mattered little to the price. The ruling cracked the door open.
XRP began to rise again. But not because retail had returned. It was because institutions were ready.
2024–2025: The ETF Domino Effect
As the legal fog lifted, the next phase of the strategy emerged: ETF filings. Between late 2024 and early 2025, a tidal wave of XRP-related ETFs were submitted to the SEC. Bitwise, 21Shares, Canary Capital, Grayscale, all preparing to tokenize the institutional demand they had already positioned for.
ProShares took it a step further. In July 2025, the SEC approved its leveraged XRP Futures ETF (UXRP), trading on NYSE Arca. Spot ETFs are expected next. And when they arrive, billions in institutional funds will pour in through regulated pipelines.
But here’s the uncomfortable truth: by the time the ETFs go live, the price of XRP will no longer be dictated by open markets. It will be dictated by the institutions who already own the majority.
Whales Now Rule the Waters
Let the data speak: over 80% of circulating XRP is now held by wallets with more than 1 million XRP. Retail no longer controls the supply. The very lawsuit that drove retail away, and claimed to protect them, became the mechanism by which control shifted to institutional hands.
They didn’t just win the lawsuit. They won the asset.
The Great Irony: Regulation as a Weapon
This is the bitter irony that few will admit. The SEC’s lawsuit, presented as a safeguard for the average investor, became the Trojan horse through which traditional finance stormed the gates of crypto. It enabled accumulation, discouraged competition, and set the stage for ETF-driven profit pipelines that will benefit the very entities that needed time to build their positions.
It was never about protecting investors. It was about keeping XRP cheap until the right people were ready to profit.
Now Comes the Cashout
With ETFs on the horizon and legal uncertainty gone, XRP is positioned to explode. And those who accumulated while the market feared SEC intervention will now ride the wave of legitimization and inflows.
Retail was forced out in fear. Institutions were let in through the backdoor.
The Truth We Weren’t Meant to See
The XRP lawsuit wasn’t just a legal battle. It was a market event. A deliberate, prolonged, precision-timed play that redistributed power and profit from the many to the few.
So the next time someone tells you the SEC is here to protect investors, remember XRP. Remember the timeline. Remember the manipulation disguised as enforcement. And remember that in this new digital economy, the real winners aren’t always the loudest voices.
They’re the ones who know how to wait, manipulate the narrative, and buy while you’re too afraid to hold.
Welcome to the truth. It’s been hiding in plain sight all along.
Social Media: The Double Standard Faced by Minority Creators in a White-Centered Digital World
Even when creators of color manage to build large, loyal audiences, they are still routinely undervalued by brands. Sponsorship deals, promotional collaborations, and product placements, the lifeblood of the influencer economy, are rarely distributed fairly.
In the age of social media, it is easy to believe that influence is democratic, that with enough followers, engagement, and content, anyone can rise. But beneath the surface of algorithms and aesthetics lies a stubborn truth: not all creators are treated equally. And often, those left out of the digital spotlight are the very ones who shaped the culture being sold back to them.
This is not just about visibility. It is about value. In the United States, where whiteness still defines what is considered universal, safe, and aspirational, creators of color remain systemically disadvantaged, even when their numbers, creativity, or influence match, or exceed, their white counterparts.
1. The Illusion of Meritocracy: Followers Are Not the Full Story
On the surface, platforms like Instagram, TikTok, and YouTube give everyone a voice. But what happens when two creators have the same reach, yet radically different opportunities?
A white content creator can post a video of themselves dancing in their kitchen or casually reviewing a snack and rack up millions of views. The same content, posted by a Black or Brown creator, may struggle to reach a fraction of the same engagement. The difference is not effort, not quality, and not even originality. It is who the algorithm favors, and more importantly, who society subconsciously validates.
Social media algorithms are not neutral. They are trained on data, and data reflects human bias. If white creators have historically received more engagement, the algorithm learns to replicate that pattern. Over time, this creates a self-reinforcing loop where whiteness becomes the default setting for success.
2. Beauty, Bias, and the Aesthetic Gatekeeping
Let us talk about appearance. On platforms where images reign, attractiveness becomes currency. But attractiveness itself is often defined by Eurocentric standards: light skin, slim bodies, straight hair, and Western features.
White creators who align with these standards are often able to build massive followings with little more than their looks and lifestyle. Meanwhile, creators of color are often expected to bring something extra, humor, intellect, talent, activism, just to be seen as equally valuable.
This creates an emotional and economic gap. White creators are rewarded for existing. Marginalized creators are rewarded only when they over-perform.
3. Culture as Commodity: The Appropriation Machine
Ironically, many of the trends that go viral, dances, slang, style, music, originate within Black, Latinx, or other marginalized communities. But when it comes to credit, visibility, and monetization, it is often white creators who benefit most.
We have seen this play out repeatedly, especially on TikTok. A Black creator starts a dance trend, only for it to be picked up and popularized by a white creator who gets invited to talk shows, brand deals, and viral fame. The original is left behind, uncredited, unpaid, and often erased.
Cultural capital flows upward, but the profits rarely trickle down.
4. Brand Bias: Equal Followers, Unequal Pay
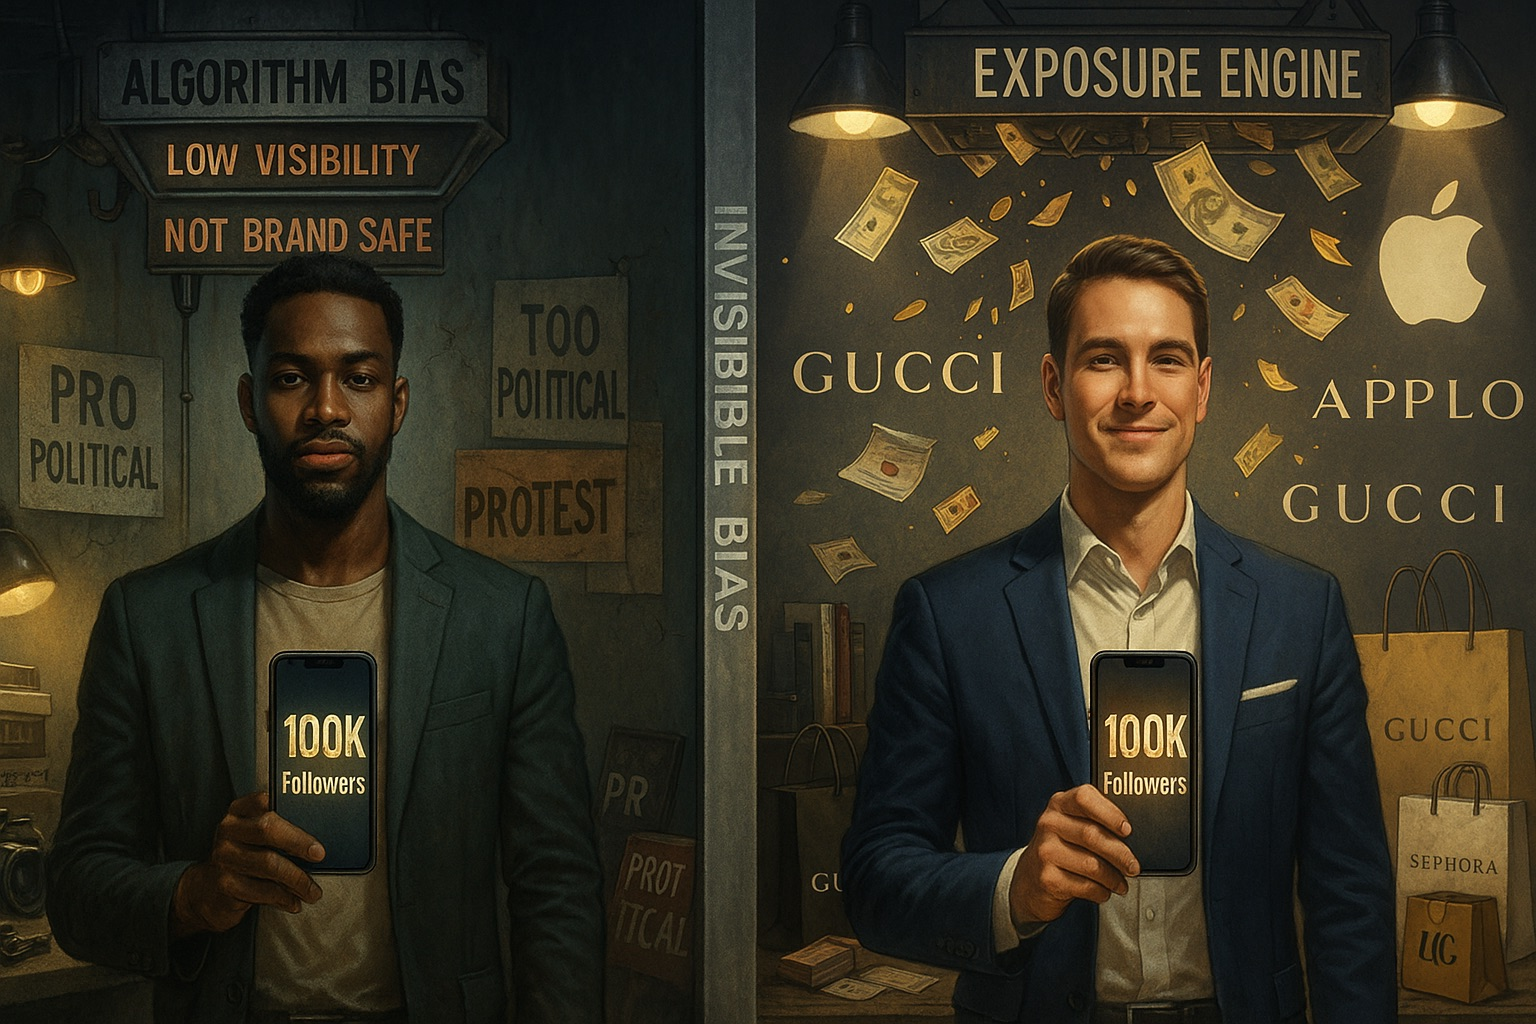
Even when creators of color manage to build large, loyal audiences, they are still routinely undervalued by brands. Sponsorship deals, promotional collaborations, and product placements, the lifeblood of the influencer economy, are rarely distributed fairly.
Why? Because brands do not just buy reach. They buy image. And when the people holding the marketing budgets are predominantly white, their choices reflect their comfort zones. This often means defaulting to creators who look like them or who feel “brand safe.”
“Brand safe” is a loaded phrase. It often translates to creators who will not talk about race, politics, or identity. It means appealing to a wide, often white, demographic. It means being palatable, non-threatening, and easy to market.
As a result, a white influencer with 100,000 followers might land a $10,000 brand deal. A Black influencer with the same stats might be offered half that amount, or passed over entirely. And when creators of color push back on these disparities, they are told they are being difficult, demanding, or unprofessional. Meanwhile, brands continue to profit from the culture without investing in the people who create it.
5. The Trap of “Universal Appeal”
There is another trap built into the system: the myth of universal appeal.
White creators are seen as relatable to “everyone.” Their content is considered broadly marketable. But creators from minority backgrounds are often treated as niche, even when their reach spans multiple demographics.
This means that minorities have to translate themselves to be seen. Whether it is switching languages, softening cultural references, or diluting their voice, they are pressured to flatten their identities to fit the mold of what brands and platforms deem accessible.
Meanwhile, white creators do not have to explain themselves, because their culture is seen as the default.
6. The Policing of Cultural Spaces: Damned If You Do…
Perhaps the most ironic injustice is what happens when minority creators finally choose to speak directly to their own communities, creating content that centers Black, Brown, or Asian experiences without catering to a white gaze.
Instead of being celebrated for cultural pride or autonomy, they are often accused of exclusion, division, reverse racism, or “communitarianism.” In short, minority creators are punished for doing exactly what white creators have always done, speak to their own audience, in their own language, from their own reality.
This discomfort often manifests in content being flagged, shadowbanned, or suppressed. It also shows up in comments and brand silence. Why? Because white audiences, and the systems built around them, are not used to being outside the message.
This creates a lose-lose situation. If minority creators code-switch or water down their message, they lose authenticity. If they remain rooted in their community, they are seen as alienating.
7. Algorithmic Censorship and Suppression
Let us be even more direct. The system is designed to reward whiteness and discipline everyone else.
There have been numerous reports and leaked documents showing that platforms like TikTok, Instagram, and Facebook have suppressed content related to Black Lives Matter, Indigenous land rights, police brutality, and LGBTQ+ issues.
Often, the excuse is “violating community guidelines,” even when the content in question contains no hate, nudity, or violence, just truth.
This disproportionate censorship not only limits reach, it forces creators of color into silence or self-censorship just to maintain their accounts or avoid being shadowbanned. Meanwhile, white creators can freely co-opt those same aesthetics or narratives, stripped of context, and be rewarded for “edginess” or “activism.”
So What Is the Solution?
The goal is not to flip the script and disadvantage white creators. It is to expose the imbalance and build systems that reward value more equitably.
That includes transparent brand deals and public pay disclosures. It means algorithm audits to ensure racial and cultural bias is not baked into promotion patterns. It means hiring diverse decision-makers on brand and platform teams. It means direct investment in underrepresented creators, not just through “Black History Month” campaigns or temporary spotlights, but long-term equity strategies.
Most importantly, it means public awareness among audiences. Who we follow, share, and uplift sends a message to the system.
Final Words: It Is Not About Likes. It Is About Liberation.
To be a minority creator in the United States today is to constantly walk a tightrope: be visible, but not too ethnic. Be proud, but not divisive. Be talented, but not threatening. Be everything, and somehow still not enough.
This is not a failure of individual creators. It is a reflection of the systems they are forced to operate within, systems built on legacy ideas about who deserves power, attention, and reward.
But creators are waking up. They are organizing, speaking out, and building their own ecosystems. Because the truth is, culture has always come from the margins.
What is changing now is the demand that credit, compensation, and control follow that culture home.
Until then, the follower count will remain a façade, one that hides the real imbalance behind the screen.



 Entertainment1 year ago

 Opinion1 year ago

 Politics1 year ago

 Tech1 year ago

 Economy1 year ago

 Sports1 year ago

 Opinion11 months ago

 Entrepreneur1 year ago